Services
Insurance Claims and SupplementsBased in Southlake, TX
Documentation, adjuster meetings and supplements on a storm claim, so the scope that gets paid matches the scope of the damage.
Get a Free Estimate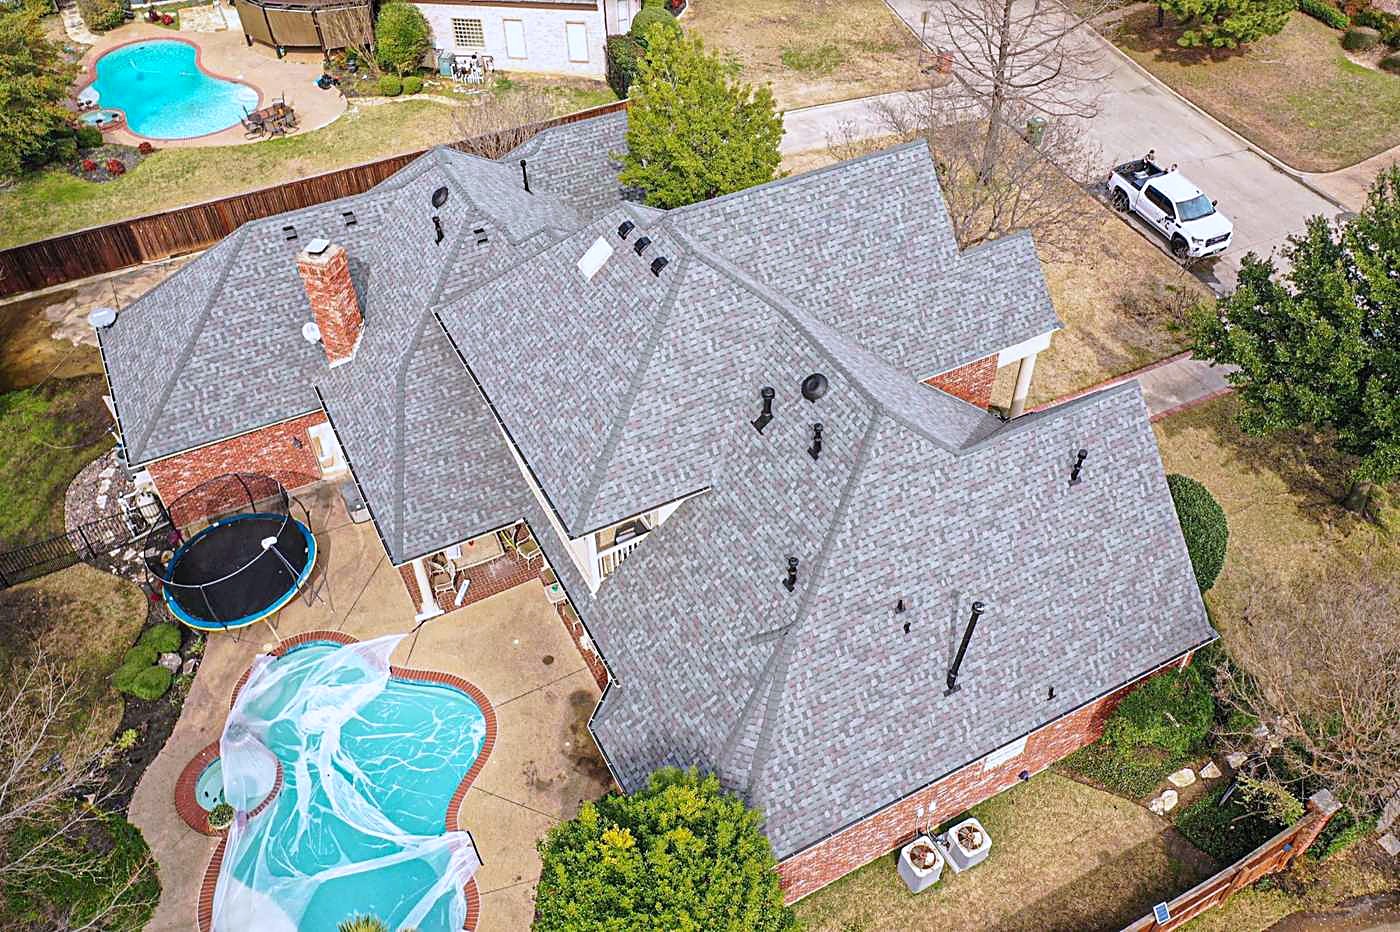
Insurance Claims
What the job actually involves.
On a hail roof the paperwork decides how much of it gets paid for. We take that as seriously as the roof.
A claim runs in a fixed order. You report the loss to your carrier. They send an adjuster, who climbs the roof, marks test squares and writes an estimate. The carrier issues a first payment, usually the actual cash value: the replacement cost less depreciation, less your deductible. The work gets done. The carrier releases the withheld depreciation once it has been shown the work was completed. The part most homeowners have never heard of sits between those last two steps.
How It Works
Call or send the form
Tell us what you are seeing and where the property is. A storm date helps if there was one.
Free inspection
About 15 to 20 minutes on the roof and in the attic, and you get a written report with photographs to keep.
The scope, in writing
What the roof needs, what it costs, and on a claim, what the carrier has and has not allowed for.
The work
Roof first, then the gutters, fence, windows or siding if the storm took those too. One company for the lot.
The Difference
Where these go wrong.
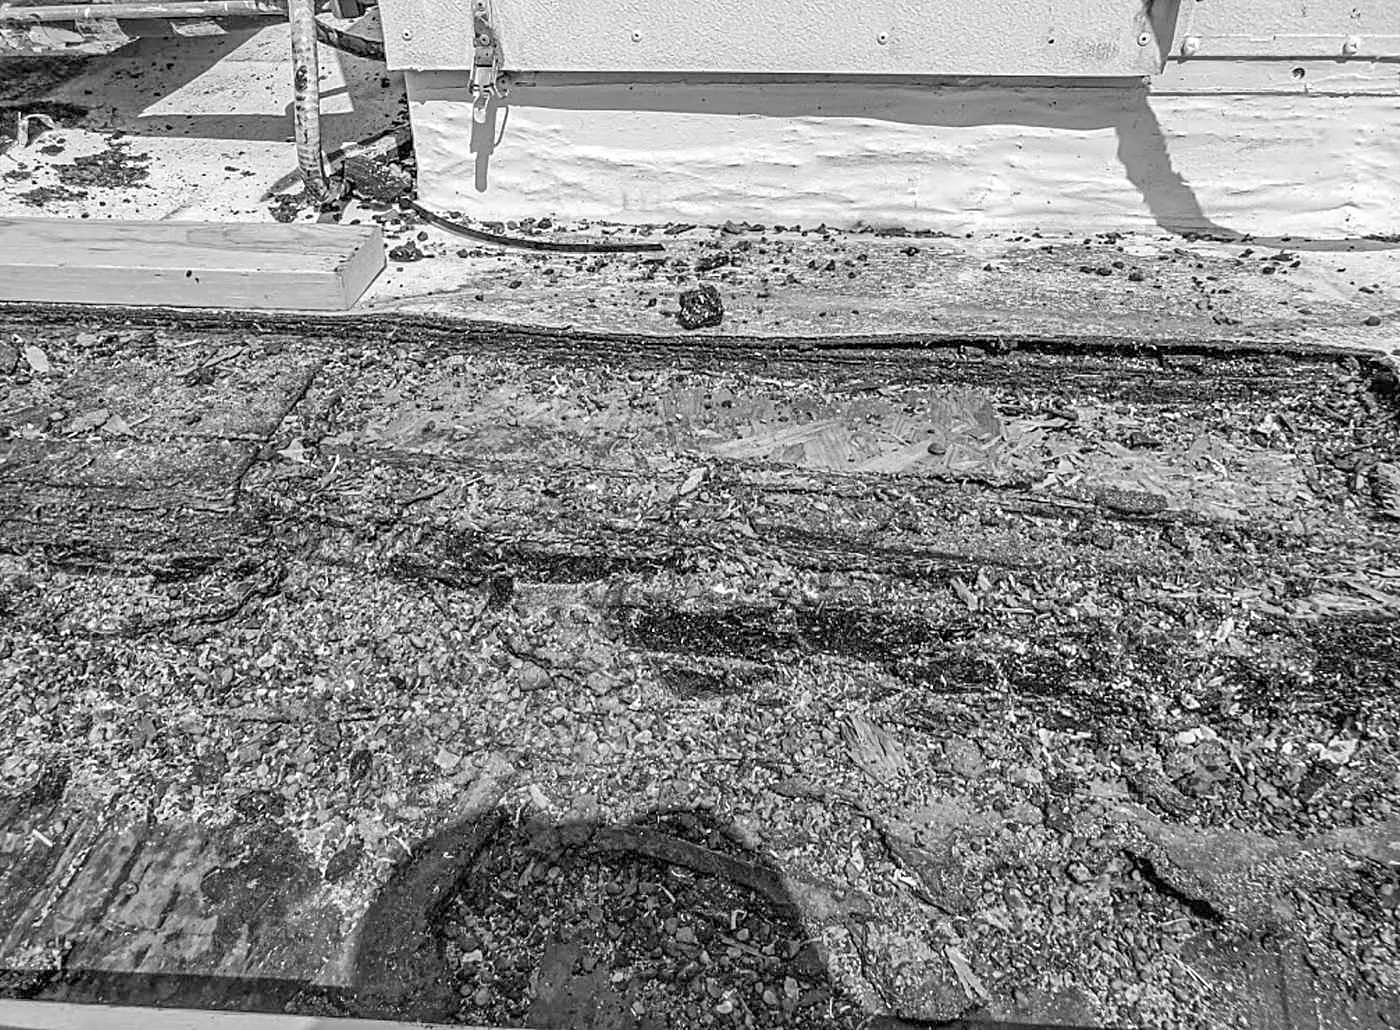
That part is the supplement. The adjuster’s first estimate is written from one visit and it routinely misses things that only appear once the tear-off starts, or that are simply not in the line items they used: decking that turns out to be rotten, ridge ventilation, ice and water in the valleys, drip edge, a code requirement the city enforces and the estimate did not budget for. A supplement is the documented request to add those to the claim, with photographs and measurements behind each one. Storm restoration, minor repairs and insurance supplementation are all part of what we do.
Being there when the adjuster is there is worth more than anything that happens afterwards. Two people on the same roof looking at the same test square agree far more often than two people reading each other’s reports a fortnight later.
One thing worth being clear about, because the trade has a bad reputation for it: your deductible is yours. A contractor who offers to absorb it, waive it or hide it in the invoice is proposing insurance fraud under Texas law, and it is the homeowner whose name is on the policy.
Get a Free EstimateRecent Work
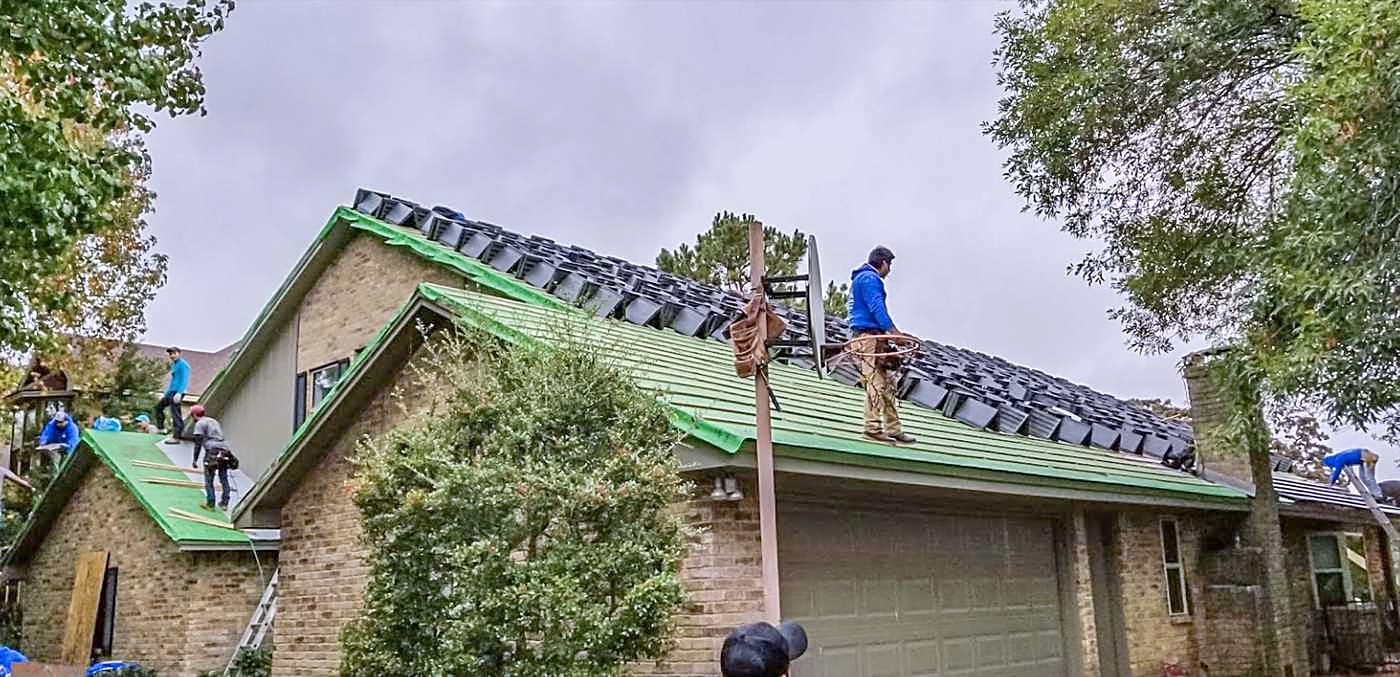
Recent work across Southlake, TX
Before You Call
Insurance Claims, answered.
Will filing a claim raise my premium?
A weather claim is not treated the same way as an at-fault claim, and in a hail year a carrier is usually adjusting rates across a whole region rather than for one policy. What is worth avoiding is filing a claim that gets denied, because the claim still appears on your history and you got nothing for it. That is the reason to have the roof looked at before you call.
What is a supplement?
A documented request to add to the claim something the adjuster’s first estimate did not include. It is normal, not adversarial: the first estimate comes from one visit before the roof is opened, and some of what a roof needs is only visible once the old one is off.
Should I get the roof inspected before I call my insurer?
It helps. A written report with photographs tells you whether the storm did enough damage to be worth a claim, and gives you a dated record of the condition. The inspection is free either way.
Can you pay my deductible for me?
No, and neither can anyone else legally. Texas law treats waiving or absorbing a deductible on an insurance job as fraud, and the exposure lands on the homeowner as well as the contractor. Anyone offering it is telling you something about how they run the rest of the job.
Who do I deal with, you or my insurance company?
The policy is between you and your carrier, so the decisions stay yours. What we do is the documentation, the adjuster meeting and the supplements, so that what gets approved matches what the roof actually needs.
Worth Reading First
More from JWC General Contractors
Insurance Claims
Every job here starts with a free inspection and a written report that belongs to you.
Let's work together
Book a free inspection.
About 15 to 20 minutes on the roof, and a written report with photographs that is yours to keep whether or not there is anything to do.
JWC General Contractors 515 W Southlake Blvd Suite 150, Southlake, TX 76092 (214) 972-4266 · info@